
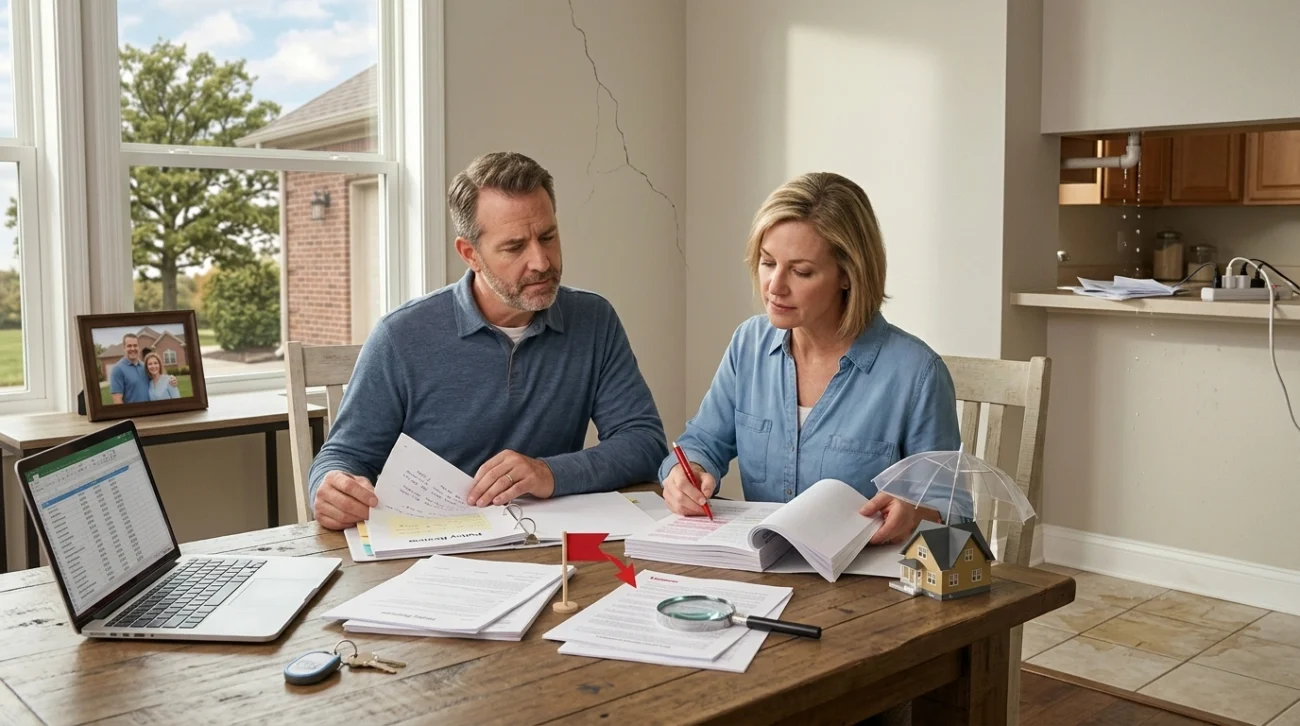
Home insurance is one of those purchases that most people make because they have to, review minimally once it is in place, and then discover the details at the worst possible moment when they are filing a claim. The gap between what homeowners assume their policy covers and what it actually covers is where the most expensive surprises tend to live.
Understanding what a standard home insurance policy includes, what the most common exclusions are, and where optional coverage fills the gaps produces better coverage decisions before something goes wrong rather than after.
What a Standard Home Insurance Policy Actually Includes
A standard homeowners insurance policy provides protection across five primary categories that together cover the most significant financial risks of owning a home.
Dwelling coverage pays to repair or rebuild the structure of your home if it is damaged or destroyed by a covered event including fire, windstorm, hail, lightning, and certain types of water damage. The coverage extends to attached structures like a garage, and typically to detached structures like a fence or a separate garage under other structures coverage. The critical number in dwelling coverage is whether the coverage limit reflects the actual cost to rebuild your home rather than its market value, a distinction that matters enormously when a claim is filed.
Personal property coverage protects your belongings including furniture, clothing, electronics, and sporting goods if they are damaged, destroyed, or stolen as a result of a covered loss. Most standard policies cover personal property on an actual cash value basis rather than replacement cost, which means the settlement reflects the depreciated value of what was lost rather than what it would cost to replace it with a new equivalent.
Loss of use coverage pays for additional living expenses including accommodation, meals, and other necessary costs if a covered loss makes your home temporarily uninhabitable. For a serious fire or structural damage that requires weeks or months of repair, this coverage is what allows you to maintain a reasonable standard of living during the displacement rather than absorbing those costs personally.
Personal liability coverage protects you against claims of property damage or bodily injury for which you are found legally responsible, including a legal defense if you are sued. This coverage applies to incidents on your property and in some cases to incidents away from your property.
Medical payments to others covers minor medical claims if a guest is injured on your property, regardless of legal liability, which handles the smaller injury scenarios that personal liability coverage may not need to be invoked for.
The Coverage Gaps That Catch Homeowners Off Guard
The exclusions in a standard homeowners policy are as important to understand as the coverages, and several of them are genuinely surprising to homeowners who have never reviewed their policy in detail.
Flood damage is the most significant exclusion in most standard home insurance policies and the one that catches the most homeowners unprepared. Damage from external flooding, including storm surge, river overflow, and heavy rainfall runoff, is not covered by a standard homeowners policy regardless of how severe the flooding is or how clearly it was caused by an external weather event. Flood insurance requires a separate policy, typically through the National Flood Insurance Program or a private flood insurer, and the purchase of that coverage cannot be rushed after a flood is imminent because there is typically a waiting period before coverage takes effect.
Earthquake damage is similarly excluded from standard homeowners policies. In California, where seismic activity is a genuine ongoing risk rather than a theoretical one, earthquake coverage is worth serious consideration for any homeowner. W Insurance offers home insurance with an earthquake coverage option through a partnership with the California Earthquake Authority, allowing homeowners to add earthquake protection to their existing policy rather than buying a separate policy through a different insurer.
Gradual water damage and maintenance-related issues are excluded from standard policies in ways that confuse many homeowners. A burst pipe that causes sudden and accidental water damage is typically covered. A slow leak that causes gradual damage over months or years because it was not discovered or addressed is typically not covered because the exclusion for poor maintenance applies. Regular inspection and prompt repair of any water issues is both a maintenance responsibility and a coverage protection.
Rental activity changes the coverage picture in ways most homeowners do not realise until it is too late. If you rent out part of your home or your entire home through a rental platform or any other arrangement, a standard homeowners policy does not cover rental-related incidents. Informing your insurer of rental activity and obtaining the appropriate policy type is the right approach rather than assuming the existing coverage extends to the rental situation.
The Optional Coverages Worth Considering
Standard home insurance leaves specific categories of personal property with lower effective protection than their value warrants, which is where the optional coverage add-ons address real gaps.
Standard personal property coverage applies sub-limits to categories including jewelry, watches, furs, firearms, money, and electronics that are often well below the actual value of items in those categories that homeowners own. Special increased limits coverage raises those sub-limits to provide more meaningful protection for valuable items in these categories. Scheduled property coverage takes this further by insuring specific items, including fine art, musical instruments, bicycles, and coin collections, to their appraised value rather than a general sub-limit.
Replacement cost coverage for personal property changes how claim settlements are calculated from actual cash value, which deducts depreciation, to replacement cost, which pays what it actually costs to replace the lost or damaged item with a new equivalent. For homeowners with relatively new furnishings and electronics, the difference between actual cash value and replacement cost settlement can be substantial.
How to Avoid Being Underinsured
The most consequential home insurance mistake is carrying a dwelling coverage limit that is lower than the actual cost to rebuild your home. Market value and rebuild cost are different numbers, and in many markets they differ significantly. A home worth $600,000 on the market may cost $800,000 to rebuild to current construction standards with current material and labor costs, and a policy written to the market value leaves an $200,000 gap that becomes visible only when a total loss claim is filed.
Reviewing the dwelling coverage limit annually and after any renovation that adds to the rebuild cost, and using current local construction cost data rather than the original purchase price as the basis for the coverage limit, ensures that the policy reflects what it would actually cost to rebuild rather than what the home was worth when the policy was first written.
Bundling home and auto insurance with W Insurance can reduce the home insurance premium by up to 20 percent, and additional discounts are available for non-smokers and for policies that have remained claim-free. The online quote process takes less than three minutes and reflects available discounts alongside coverage options.
